Showing posts with label Keynesianism. Show all posts

Saturday, February 11, 2012

19th century vs. 20th century

Someone, in a conversation with me, has claimed that if we went back to the gold standard, or at least, if the Central Bank did not inflate the currency, there would be zero economic growth (or even a recession).

I countered that we certainly did not observe this happening in the 19th century, when US and UK economies grew very rapidly.

He answered: Yes, they grew, but not nearly as rapidly as in the 20th century.

Let's see if he is right. One thing about the growth of the economy is that it is an auto-catalytic process: the product catalyzes the reaction, so the more product you have, the faster the reaction rate. If you start off with $100, your business will grow slower than if you start off with $100,000. (Your business will grow as a result of you re-investing a portion of your profit. The more you invest, the more it will grow. But since your profit from $100,000 will be greater than from $100, your business growth rates will be different.)

To correct for this, it's useful to look at the logarithm of growth, as opposed to pure growth. For those who don't know much math, logarithm is a function inverse of exponential function. So, if a graph shows exponential growth (as in the case of growth rate of an auto-catalytic reaction), its log will show a straight line.

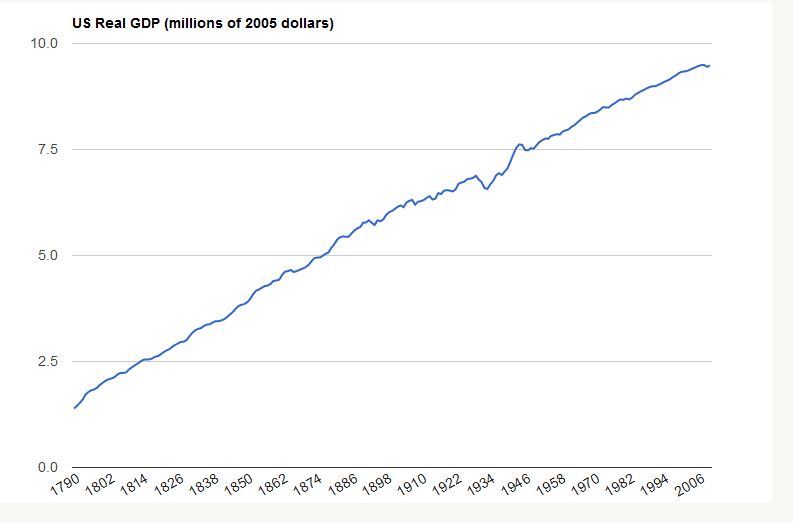
After this introduction, let's look at the data. The following figures show growth of GDP in the United States, from 1790 to 2010. The graphs are logs (including the second one, despite the label). "Real GDP" is adjusted for inflation, as I understand (I may be wrong).

I don't know about you, but to me, growth rates seem very comparable. And GDP is just the first measure of growth that came to my mind and not necessarily the "purest" measure of the growth of "real wealth".


(Source: Measuring Worth > Datasets > US GDP)


This is also a rather interesting graph — Consumer Price Index, in logs:


Here are raw data:


If you go to the interactive graph, you will see that the prices rose rapidly when US entered a war (the US Revolution in 1776, the War of 1812, the War of Northern Aggres... I mean, the Civil War in 1861, and the First World War in 1916). Then, FDR took away Americans' gold, and the prices rose for the duration of the Great Depression and the Second World War. Then, in 1967, the last tie to gold standard was cut, and the prices were rising ever since.

So, basically, the effect of US government on the prices of products and services is similar to that of a war.

Yeah, but if there was no inflation, there would be no growth, right? Go back to the beginning of the thread.

Some more background:

First, this: http://www.tomwoods.com/inflation/

Second, this:

Thursday, January 29, 2009

Despite the President’s sincerest assurances...


… not everyone is brain-dead. Some still have some seichel attached to their middois (full version).

(It would look even nicer if there wasn’t a period at the end of that sentence.)

Thursday, October 2, 2008

Economists and the vortex of power


Today, in the car:
— So, what, everyone is an idiot? All the politicians, all the economists in the Washington think this is the right thing to do, and they’re all idiots? How can all of them be idiots?
— What about the Soviet Union? Were all the politicians, economists, etc. idiots?
— In the Soviet Union — yes. Here it’s different.
— It’s not different for those that want to turn the US into a Socialist state.
…
— You didn’t like everything going on in the Soviet Union, did you? The corruption, the black market, the country turned into a prison, nobody caring about anything…
— Yeah, but that was politics.
— The politics is the result of the economic system. Whenever socialist goals are set, the society starts to change — go down the drain. In order to “regulate” that, the government has to implement all the “wonderful” political tools of Socialist era. Politics is always closely tied to the economy and vice versa.
Right now, I was listening to Joe Salerno. He said the exact same thing: that even the economists like Bernanke, who seemed to understand what was going on, right now are being sucked into the idiocy. The explanation is simple: once you get involved with the government, you start thinking in terms of political self-preservation and get sucked-in into the centralized vortex of regulationism. The closer you get to the vortex, the more you’re influenced by it, the sooner you loose the independence of thinking.

Very interesting conversation. He also discussed Keynesianism (“It’s dead from the neck up”) — a great enabler of the state power, the credit crisis, and the hysterics. Bottom line: allow the economy to restore itself. In the time of recession, the credit cannot be loosely available — and it became loose to begin with because of the Fed.

First, do no harm.